
Financial statements are pivotal tools for business owners, investors, and stakeholders to assess the financial health of an organization. Mastering the preparation of these documents is essential for making informed decisions. This article provides a comprehensive, step-by-step guide to effectively preparing financial statements, ensuring accuracy and compliance with accounting standards. Understanding the mechanics of financial statement preparation can equip individuals with the knowledge to enhance their financial acumen and contribute to sound financial management practices.
Understanding the Types of Financial Statements
Financial statements come in various types, each serving a unique purpose. The primary statements include:
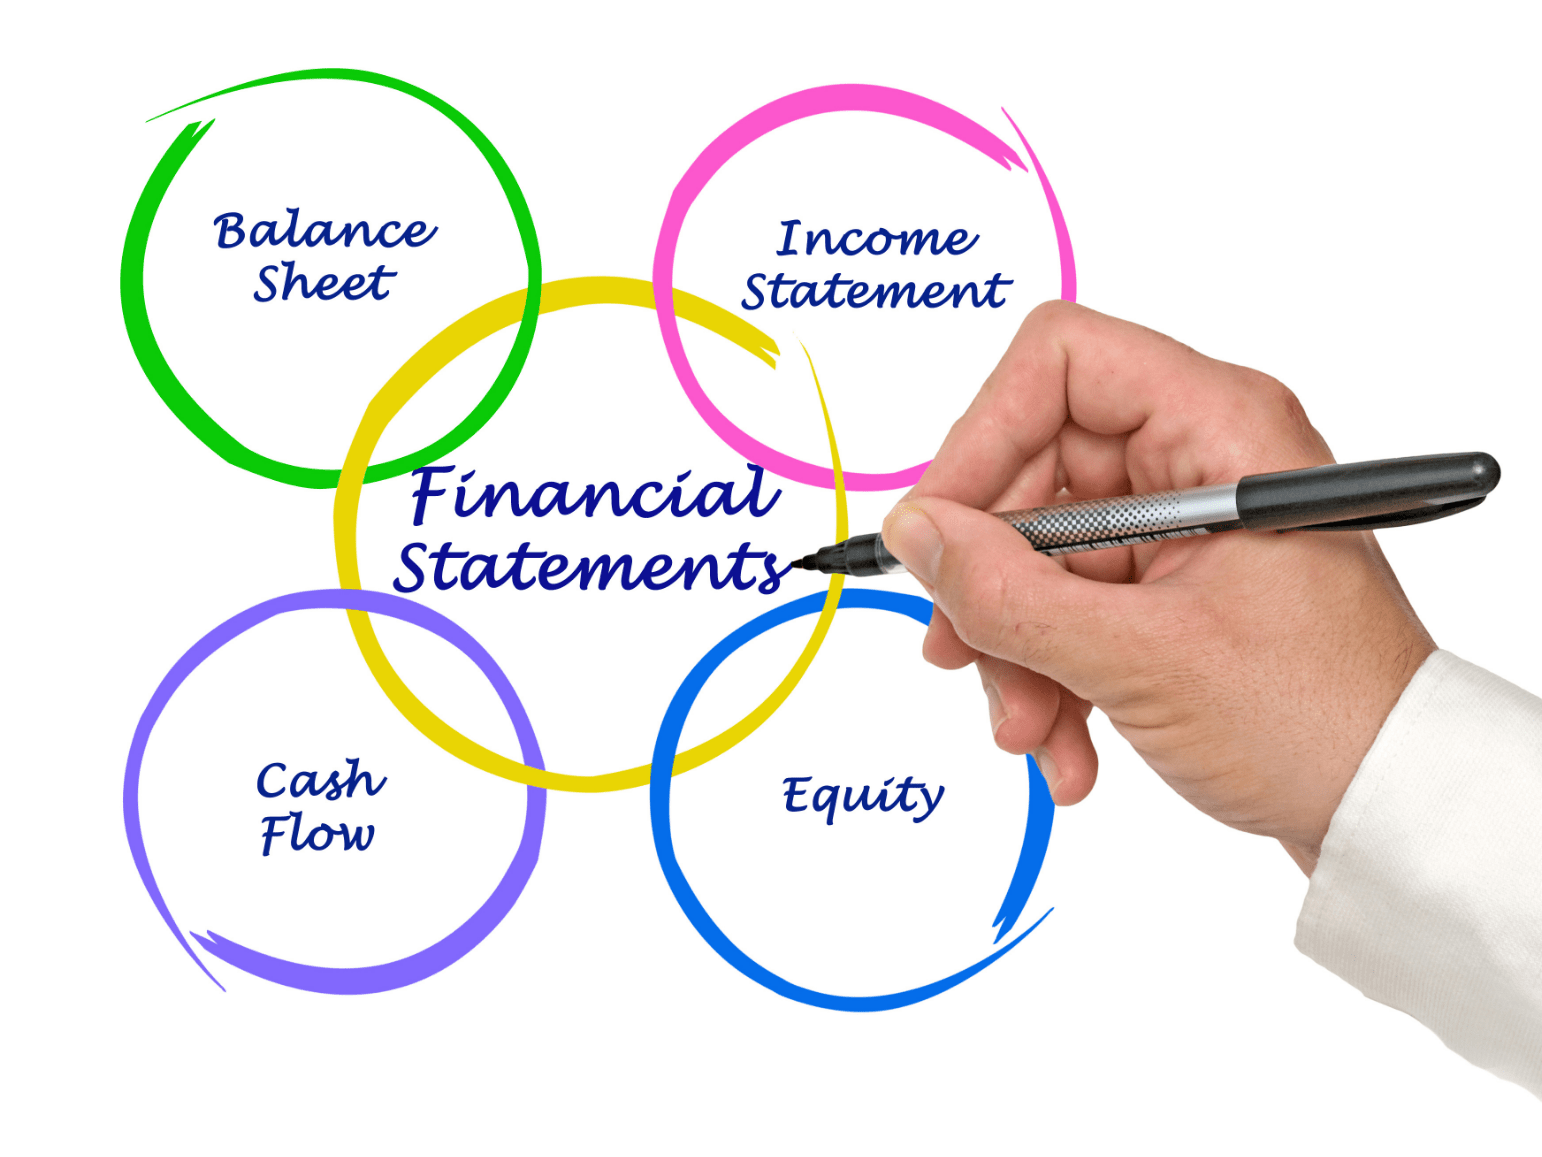
- Balance Sheet: This statement provides a snapshot of an organization’s financial position at a specific point in time, detailing assets, liabilities, and equity.
- Income Statement: Also known as the profit and loss statement, it shows the company?s financial performance over a period, highlighting revenue, expenses, and net profit or loss.
- Cash Flow Statement: This statement tracks the cash inflows and outflows, offering insights into the company’s liquidity and financial flexibility.
- Statement of Changes in Equity: It reflects changes in the company’s equity over a reporting period, considering aspects like retained earnings, issued shares, and dividends.
Understanding these statements is critical for accurate preparation. Find additional information here.
Step-by-Step Guide to Preparing Financial Statements
Step 1: Gather Financial Data
Collect all necessary financial data, including transaction records, bank statements, and previous financial statements. Ensure the data is complete and up-to-date for an accurate representation of financial activities. Read more about this topic.
Step 2: Prepare the Trial Balance
The trial balance is a crucial step in the accounting cycle that lists all ledger accounts and their balances. It helps in ensuring that debits and credits are balanced. Any discrepancies should be investigated and corrected before moving forward.
Step 3: Adjust Entries
Adjusting entries are necessary to account for accrued and deferred items. This includes recognizing revenue earned but not yet recorded and expenses incurred but unpaid. Proper adjustments ensure the financial statements reflect true financial performance. Learn more in this detailed guide.
Step 4: Prepare Financial Statements
With the trial balance adjusted, financial statements can be prepared. Start with the income statement, followed by the balance sheet, and conclude with the cash flow statement and statement of changes in equity. Ensure that all figures are accurately recorded and reconcile with the trial balance.
Step 5: Review and Analyze
Once the financial statements are prepared, conduct a thorough review to ensure accuracy and completeness. Analyze the statements to gain insights into financial trends and performance metrics. Explore further insights here.
Common Pitfalls and How to Avoid Them
Preparing financial statements can be fraught with challenges. Here are some common pitfalls and tips to avoid them:
- Inaccurate Data Entry: Double-check all entries for accuracy to prevent errors in the financial statements.
- Neglecting Adjustments: Failing to make necessary adjustments can lead to misstated financial results.
- Overlooking Documentation: Maintain thorough documentation to support all figures and adjustments.
- Ignoring Compliance: Stay updated on accounting standards and regulations to ensure compliance.
Addressing these issues proactively can enhance the reliability of financial statements. Find additional information here.
Mastering the preparation of financial statements is a vital skill for financial management. By following these structured steps and remaining vigilant against common pitfalls, individuals can create reliable and insightful financial documents that support sound business decisions.